What the Chips Act did not fix: the case of Spain
Spain set aside EUR 12.25 billion for semiconductors and by late 2025 had spent 7% of it. Why the big-fab model did not fit, and what changes with the Chips Act 2.0.
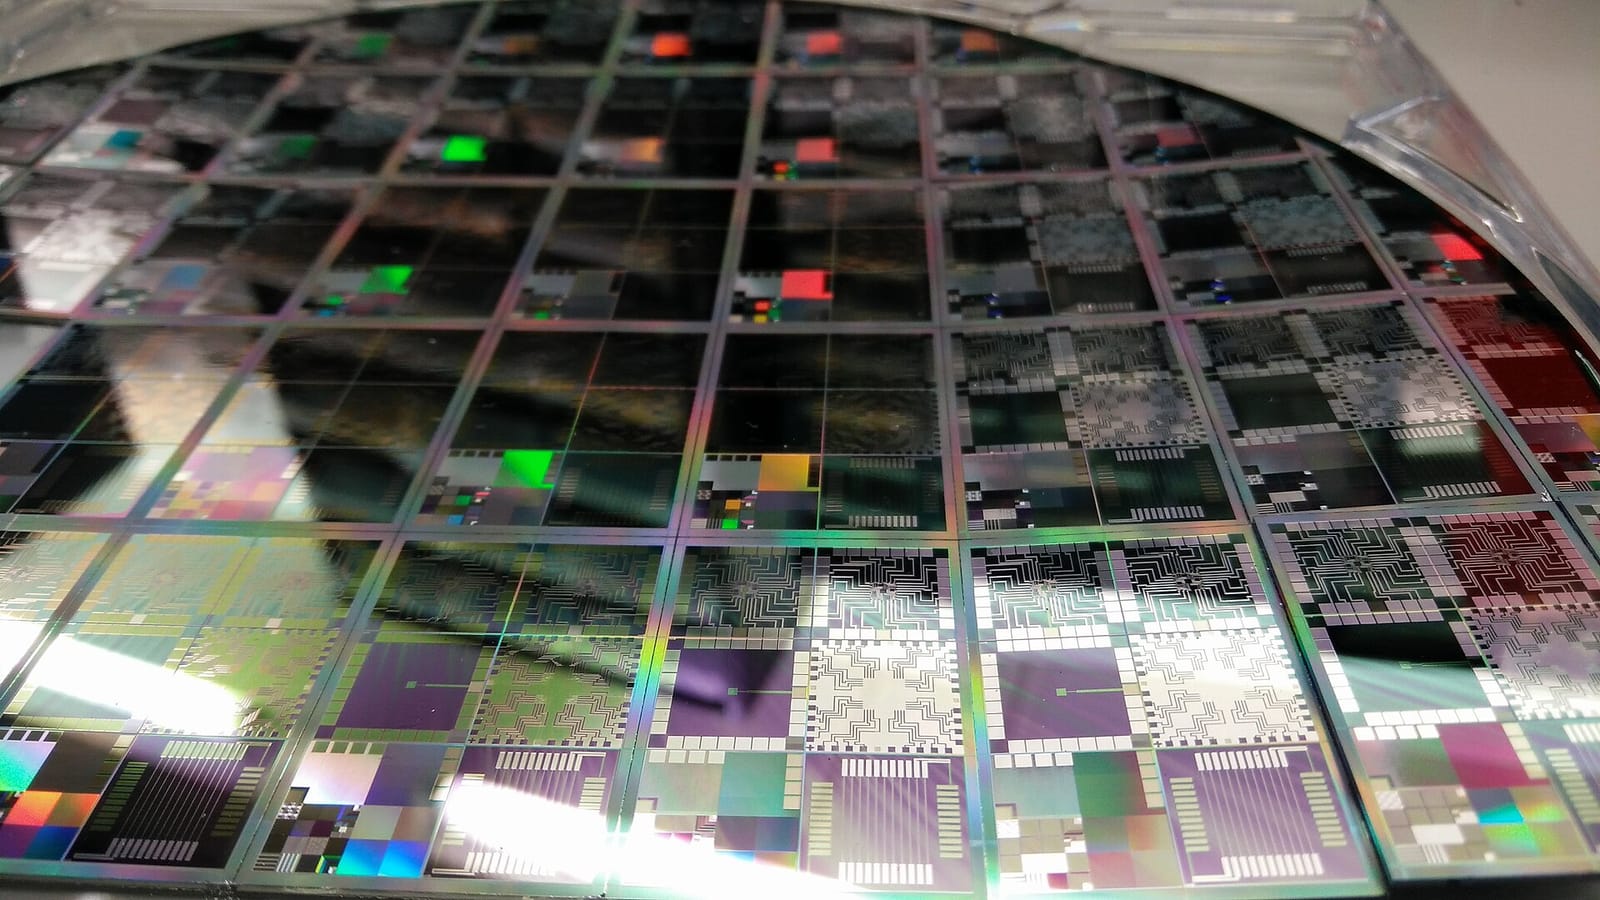
In 2022 Europe set itself the goal of producing 20% of the world’s chips by 2030. Spain, through its PERTE Chip programme, tried to ride that wave with the largest line in its recovery plan. Four years on, the European target is considered out of reach and the plant that symbolised Spain’s bet will not be built. The Commission has just proposed a Chips Act 2.0. It is worth understanding first what went wrong.
KEY MESSAGES
- The European Court of Auditors estimates that the EU will reach at most 11.7% of global market share by 2030, far from the 20% target.
- In Spain, 76% of the PERTE Chip was earmarked for building fabs, precisely the axis with the weakest execution (around 10%).
- The Chips Act 2.0, proposed on 3 June 2026, shifts the focus towards demand, design and AI chips. For Spain, it may be a more realistic second chance.
A European target that was never realistic
Regulation (EU) 2023/1781, known as the Chips Act, was designed after the chip shortages of the pandemic. It had three pillars: the Chips for Europe Initiative (research, pilot lines, design), a framework to attract large fabs with state aid, and a crisis monitoring mechanism.
In April 2025 the European Court of Auditors delivered a harsh verdict. Europe’s share was 9.8% in 2022 and, on current trends, would be around 11.7% in 2030. Reaching 20% would require roughly quadrupling production capacity. The money was not there: of the EUR 86 billion mobilised, the Commission contributed only about 4.5 billion. The world’s largest manufacturers, by contrast, invested EUR 405 billion between 2020 and 2023. ECA member Annemie Turtelboom summed it up by calling for a “reality check”.
Spain: a big budget, few fabs
The PERTE for Microelectronics and Semiconductors is the largest strategic project in Spain’s Recovery Plan: EUR 12,250 million until 2027. It was organised in four axes, but the split was very uneven: EUR 9,350 million, or 76%, went to building chip fabs.
That is the axis that failed. According to an analysis by Funcas and AFI with data to September 2025, only EUR 880 million had been spent (7% of the total) and around 2,500 million awarded (20%). The science, design and tech-industry axes were above 60% execution. The fab axis stood at around 10%.
The most visible case was Broadcom. In July 2023 the US company announced it was considering investing about USD 1 billion in a plant in Spain. Talks stalled in early 2024 and in July 2025 were reported to have collapsed. The PERTE’s anchor project was gone.
Why it did not fit
The most convincing explanation came from the industry association AESEMI: the plan was designed to compete with silicon fabs in the United States, China or Taiwan, and that model does not fit Spain’s industrial ecosystem. A leading-edge fab needs a supplier chain, specialised talent and nearby customers that Spain did not have. Public money can cover part of the investment, but it cannot create that environment in three years.
Timing made it worse. Recovery Plan funds must be committed on very short deadlines, designed for works and calls for proposals, not for years-long negotiations with multinationals. The result is a paradox: the most expensive axis was the least compatible with the instrument financing it.
There is, however, a less pessimistic reading. The design and science axes have made progress, and smaller, more specialised projects have emerged, such as integrated photonics in Galicia. It is not the big fab that was promised, but it may be a more sustainable niche.
The Chips Act 2.0: a change of approach
On 3 June 2026 the Commission presented the Chips Act 2.0 (COM(2026) 504), which would repeal the 2023 regulation. Its own explanatory memorandum acknowledges that the EU still produces less than 10% of the world’s semiconductors.
| Chips Act (2023) | Chips Act 2.0 (2026 proposal) | |
|---|---|---|
| Approach | Supply: attract fabs | Supply and demand |
| Goal | 20% of global share by 2030 | Reduce strategic dependencies |
| New instruments | — | Public procurement with security-of-supply criteria, demand forum, strategic project for AI chips |
| Regions | — | European Semiconductor Region of Excellence label |
| Crisis | Monitoring mechanism | Powers to request data and prioritise orders, triggered by the Council |
The shift matters for Spain. If the new policy rewards design, demand from user sectors (automotive, energy, defence) and regional specialisation, the country has better prospects than in a race to build the most advanced fab.
WHAT TO WATCH
- The negotiation of the Chips Act 2.0 in the European Parliament and the Council, and the position Spain takes.
- What happens to unspent PERTE Chip funds when the Recovery Plan closes.
- Whether any Spanish region applies for the Semiconductor Region of Excellence label.
- The actual funding of the new regulation in the next multiannual financial framework.
The lesson of the first Chips Act is not that Europe should not have a semiconductor policy, but that targets must match the budget and the existing industrial base. Whether Spain makes the most of this second chance will depend on not repeating the mistake of betting everything on a single fab.
Main sources. Regulation (EU) 2023/1781; European Court of Auditors, special report 12/2025; European Commission, proposal COM(2026) 504 (3.6.2026); Spanish Recovery, Transformation and Resilience Plan (PERTE Chip); Funcas and AFI, cited by El Independiente (24.4.2026); Xataka and La Ecuación Digital on Broadcom (in Spanish).